
 Log In
Long-term care (LTC) planning works best when you match the solution to each client’s goals, health, finances and care preferences. Start by defining the planning problem, assess the client’s circumstances, narrow the solution types and compare contract details before making a recommendation.
Three different clients have the same need — to plan for the possibility of expensive long-term care (LTC).
But making the same recommendation could be problematic. There is no single “best” long-term care solution. Asset-based LTC insurance, traditional LTC insurance, life insurance with LTC benefits, annuity-based LTC and short-term care insurance each solve different planning problems.
So how do you determine which LTC planning solution is the right fit for each client? And where do you start?
A process that stays focused on the client will help you avoid a mismatch, so you’ll land on an LTC strategy that reflects their priorities and circumstances.
Today’s broader range of LTC planning solutions gives independent insurance agents and financial advisors more ways to address the risks that extended care presents to clients’ financial plans and lives. And more choices can help more clients, meaning you can grow your business — but only if you know how to match the solution to the situation.
To match clients with the right solution for their needs, follow these four basic steps:
- Define the client’s planning problem
- Assess the client’s individual circumstances, including health
- Match the client’s needs and circumstances to possible solution types
- Compare the actual contract details
1. Start by Defining the Client’s Planning Problem
Don’t start the conversation with an LTC product.
For too long, insurance and financial planning professionals have conflated “long-term care planning” with only “long-term care insurance.” As the LTC market has evolved, so must your thinking. Traditional LTC is only one of many solutions now available — so don’t limit your sales to only one possible solution.
The right approach starts by identifying the client’s planning problem or their goals.
Ask the client what outcome they want the plan to support. Is the primary concern protecting retirement income from care costs? Preserving assets for a spouse? Leaving a legacy for heirs? Helping make it possible to remain at home? Creating at least some protection without overextending the budget?
Health is the first filter. A client’s health and underwriting eligibility may determine which LTC solutions are available and whether an informal underwriting inquiry should come before a product discussion.
2. Assess the Client’s Individual Circumstances
With the planning objective in view, assess the factors that shape which solutions are realistic. Consider the client’s:
- Age
- Health and likely underwriting path
- Income
- Assets and liquidity
- Existing life insurance or annuities
- Available family support
- Care preferences
- How soon the client needs to act
For example, a client may prioritize aging at home. Next, assess whether that client has nearby family, access to local home-care services and sufficient cash flow or assets to support the waiting period and any remaining care costs.
The client’s answers about what they want the plan to accomplish — combined with your assessment of their circumstances — help narrow the solution types that deserve a closer look.
3. Match the Client’s Needs and Circumstances to Possible Solution Types
A mismatch can cause premiums to become unsustainable, benefits to not keep pace with local costs, or coverage to not work as the client expects when care is needed.
Finding the right match is easier because the range of available LTC planning solutions continues to expand. According to LIMRA, annuity/LTC combination-product sales reached a record in 2024, increasing more than 50% year over year. A LIMRA/EY study also found that 63% of consumers express a need for LTC-focused insurance and that life/LTC combination products have become the leading private LTC insurance solution.
Here, we walk through several client profiles to show possible solution matches.
Client Profile: Has assets to reposition and wants comprehensive LTC protection with value across outcomes
Asset-based LTC insurance may use a life insurance or annuity chassis. The right fit depends on the client’s funding source, desired LTC protection, liquidity needs and legacy priorities.
It may be a strong fit for mass-affluent or high-net-worth clients in standard health who have cash value, liquid assets or other funds they are willing to reposition to address long-term care planning.
What Is the Difference Between Asset-Based, Linked-Benefit and Hybrid LTC Insurance?
These terms often overlap. Hybrid LTC is a common umbrella term for products that combine long-term care benefits with life insurance or an annuity. Linked-benefit LTC describes that combined product structure. Asset-based LTC describes the planning approach, using assets, cash value or income to fund LTC-focused protection that may also provide value if care is not needed.
A life-based asset-based LTC product is generally a linked-benefit hybrid solution. It is not necessarily the same as simply adding an LTC rider to a life insurance policy purchased primarily for death-benefit protection.
These linked-benefit solutions are designed to provide meaningful long-term care protection while addressing common concerns about traditional LTC insurance. Depending on the policy, clients may have access to benefits for qualifying care, a residual death benefit, cash value, return-of-premium features or other value if they do not need care.
This can be particularly appealing to clients who want comprehensive LTC protection but are uncomfortable with the possibility of paying premiums for a benefit they may never use. The life insurance component is part of the policy mechanics; the planning conversation should begin with the client’s LTC protection goals, not solely with the death benefit.
As with every LTC solution, funding design, benefit structure, inflation protection, underwriting and liquidity provisions vary by policy.
Client Profile: Wants comprehensive LTC protection through premium-based coverage
Traditional LTC insurance remains an important option for clients who want comprehensive, dedicated protection and prefer to fund it through ongoing premiums rather than repositioning assets.
Traditional LTC policies can offer customizable monthly benefits, benefit periods and inflation protection. For some clients, they may provide a cost-efficient way to create a substantial pool of benefits for qualified long-term care.
The tradeoff is straightforward: Traditional LTC insurance is designed specifically to help cover qualifying long-term care costs. If the client never uses it, there is generally no built-in death benefit, cash value or remaining contract value. Some policies offer an optional return-of-premium rider at death that may return some or all premiums paid, subject to contract terms and added cost.
This can be a strong fit for clients whose primary goal is protecting retirement income and assets from care costs, without making legacy value a central part of the strategy.
Client Profile: Has a life insurance need and wants to add LTC benefits
Some clients need permanent life insurance and also want access to benefits if they experience a qualifying long-term care event. For these clients, a life insurance policy with LTC benefits or a chronic illness rider may be worth evaluating.
This approach can help address more than one planning need in one policy. However, it should not be treated as automatically interchangeable with a dedicated LTC or asset-based LTC solution. LTC benefit design, available leverage, death benefits, cash value, inflation options and underwriting can vary significantly by policy.
The key question is whether the client’s life insurance need and LTC planning goals are both substantial enough to support this type of design.
Client Profile: Owns an annuity and needs a care-funding strategy
An existing nonqualified annuity can be an important part of an LTC conversation — especially when the client has substantial deferred gains, limited need for additional income from the contract or concern about the tax impact of future withdrawals.
A hybrid annuity/LTC solution may provide retirement-income potential with LTC benefits. For some clients, it can create an asset-based way to address care costs while retaining a remaining value for beneficiaries, subject to contract terms.
This may be particularly relevant for clients who want to use existing assets instead of taking on another recurring premium or face health issues that make life-based coverage more difficult to obtain.
That does not mean every annuity should be repositioned. Before recommending a change, review surrender charges, tax basis, guarantees, income needs, replacement suitability and the client’s overall retirement plan. For a deeper look at this approach, read Help Clients Fund Long-Term Care and Save Taxes at the Same Time: LTC Annuity Hybrids.
Client Profile: Needs limited-duration protection help addressing a long waiting period
Some clients cannot afford — or do not need — a comprehensive LTC strategy. Short-term care insurance may be worth considering when the client wants help with a limited period of qualifying care or needs to plan for costs during a longer elimination period in other coverage.
Short-term care is not designed to replace comprehensive LTC protection. But, depending on the product design and underwriting outcome, it can be a practical option for clients with a tighter budget, older age or health limitations who still want to reduce potential out-of-pocket costs for a covered care need.
Benefit duration, care settings, waiting periods and eligibility requirements vary by contract.
With short-term care, the right question is not, “Is this as good as a traditional LTC policy?” It is, “Does it provide meaningful protection for a risk this client would otherwise bear alone?”
4. Compare the Contract, Not Just the Product Category
Traditional LTC, hybrid life/LTC, hybrid annuity/LTC and short-term care insurance are categories — not identical products.
Before recommending any solution, compare the details that affect how it will work for the client:
- Qualification requirements and covered care settings
- Underwriting requirements
- Monthly benefit amount and benefit duration
- How the monthly benefit and inflation protection align with the projected local cost of care in the client’s preferred setting, whether at home, in assisted living or in a nursing facility, at the age they are most likely to need care. (Because many LTC claims begin in a client’s 80s, compare the benefit against projected future costs, not only today’s prices.)
- Premium funding and flexibility
- Death benefit, cash value or remaining contract value
- Liquidity, surrender provisions and access to funds
- Tax treatment and the need for tax-advisor input
- State availability and product-specific limitations
That comparison is where an advisor adds real value. Clients do not need a product dump. They need a clear explanation of the tradeoffs that matter to their own retirement plan.
When appropriate, showing clients more than one design can make the tradeoffs easier to understand. For example, you may compare a leaner option designed to address a core risk with a more comprehensive design that provides greater benefits or inflation protection. The purpose is not to create a one-size-fits-all, two- to three-option presentation; it is to help clients see what changes when their priorities, budget or desired protection level changes.
Support For All Your LTC Planning Needs With Clients
Senior Market Sales® (SMS) provides all the support today’s insurance and financial planning professionals need to match the right LTC solution to their clients’ needs, whether you’re just starting or experienced.
Access the SMS Long-Term Care Solution Comparison Guide
SMS’ “Long-Term Care (LTC) Solution Comparison Guide” is an easy-to-read, at-a-glance reference designed to help you match the right solution for each client’s individual situation. You can use it after you’ve identified a client’s planning problem and after you’ve assessed the individual circumstances to point you in the right direction. Or you also can review it while thinking of your entire client roster to spark ideas of existing clients who might be candidates for LTC planning.
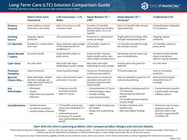
Compare traditional LTC insurance, hybrid life/LTC, hybrid annuity/LTC and short-term care insurance before your next client conversation.
Help Clients Start the LTC Conversation
 SMS Financial Solutions has a new, easy-to-read, client-facing LTC guide that helps explain the risk of needing long-term care in retirement. This non-carrier piece can be branded with your contact information and logo, giving you a useful way to break the ice and begin a more productive planning conversation. The guide is free and available to advisors with a MySMS account. Register for a MySMS account. Already registered? Log in here to get the guide.
Build Your Confidence Before the Case Review
 If you are newer to LTC planning, start with the foundations. SMS offers long-term care training through the Learning Academy to help agents and advisors build confidence in client conversations, product concepts and case design.
For more perspective on adding LTC planning to your practice, check out these SMS blogs:
- Long-Term Care in Retirement Planning: What Financial Advisors and Insurance Agents Need to Know
- How Can I Incorporate Long-Term Care Planning Into My Business?
- How Long-Term Care Expenses Can Trigger a Tax Spiral in Retirement
Find the Right Long-Term Care Solution for Each Client
Need help evaluating an LTC or hybrid case?
You don’t have to be an expert. SMS’ LTC, annuity and life insurance experts can help you identify solutions, compare them, assess underwriting fit before submitting a case and take it to the finish line with you. Whether you are reviewing a traditional LTC case, a life/LTC hybrid or an existing annuity, SMS Financial Solutions can help you with products, underwriting and case-design support. Call SMS at 1.888.456.8884, or fill out this form for a marketing consultant to reach you.
Share this blog post:


